Chapter 5 - THE SIGNATURE I NEVER GAVE
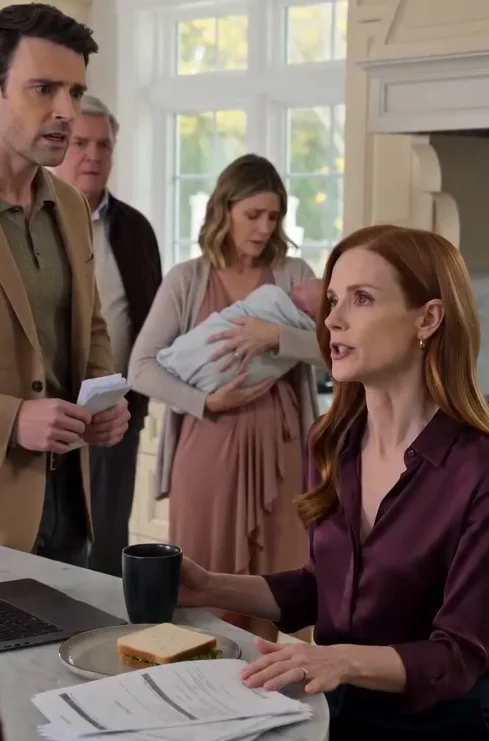
I called an attorney before I called Daniel a criminal.
That distinction mattered.
People get emotional around signatures.
Banks rely on documents.
So do courts.
Facts first.
My attorney, Laura Bennett, met me that afternoon.
The loan document was electronic.
My signature had been inserted through an online process.
The verification email address belonged to our shared household account.
Daniel had access.
So did I.
That did not prove who clicked anything.
The phone number used for verification?
Daniel’s.
That mattered.
Laura looked at him across our dining table.
He had agreed to sit for the conversation.
“Did Ms. Reed authorize you to sign or submit this guarantee?”
“No.”
“Did you believe she would?”
Daniel swallowed.
“Yes.”
I laughed once.
Laura did not.
“Did she ever tell you that?”
“No.”
“Then why is her signature here?”
Daniel stared at the paper.
“I thought it was only a preliminary application.”
Mark had told him the bank needed “household support” to approve the commercial credit.
Daniel uploaded our tax return.
Income proof.
Then clicked through forms.
He claimed he did not realize the platform converted my electronic acknowledgment into a guarantor signature.
Maybe.
Maybe not.
The bank would investigate.
I refused to invent certainty.
But one thing was certain.
He used my financial information without permission.
Again.
Then Megan arrived.
Mark came with her.
For the first time since this started, all four of us sat at one table.
Mark looked terrible.
Good.
Megan asked him:
“Did you know Esme hadn’t agreed?”
He looked at Daniel.
Wrong move.
“Mark.”
“Yes.”
The word barely came out.
Megan closed her eyes.
“You knew?”
“Daniel said she’d be okay with it.”
I said:
“Daniel has apparently spent a year telling people what I’ll be okay with.”
Mark looked ashamed.
“I should have asked.”
“Yes.”
No comfort.
Then he admitted the business had not simply failed because contracts disappeared.
He expanded too fast.
Bought equipment before revenue existed.
Leased a second van.
Paid a consultant.
Then used credit cards to cover payroll.
“How much debt total?” Megan asked.
“Eighty-three.”
She stared.
“I thought fifty-eight.”
“That’s the bank loan.”
“What’s the rest?”
Mark looked down.
“Cards.”
Megan covered her face.
Two newborn twins.
Unpaid maternity leave.
And a husband hiding eighty-three thousand dollars in failed-business debt.
She whispered:
“Why didn’t you tell me?”
Mark’s answer sounded familiar.
“I thought I could fix it before you found out.”
The kitchen became completely quiet.
I looked at Daniel.
He looked at me.
There it was.
The philosophy that had infected both men.
Hide the problem.
Use available money.
Repair it before wives notice.
Then it doesn’t count.
Laura arranged for the lender to freeze any collection action tied to my disputed guarantee while it reviewed authorization.
That did not erase Mark’s debt.
It protected me while facts were sorted.
Megan turned to Daniel.
“You promised my brother-in-law’s wife’s income before even telling me our situation.”
Daniel looked frustrated.
“I was trying to keep you from panicking.”
“I’m panicking now.”
Fair.
Then Mark said something unexpected.
“Daniel also told me he could get money from the house.”
I became still.
“What house?”
Mark looked at me.
“Yours.”
Our home.
Daniel closed his eyes.
I stared.
“What did you tell him?”
Daniel whispered:
“That we had enough equity.”
“Why would that matter?”
Silence.
Laura looked at him.
“Mr. Reed?”
Then Daniel admitted he had requested a home-equity prequalification three weeks earlier.
Not a completed loan.
Not a signed closing.
But he had started the process.
Amount requested:
$120,000.
Enough to wipe out Mark’s bank loan.
Daniel’s credit-card debt.
And restore some of our missing emergency savings before I noticed.
May you like
His plan had not been half my salary alone.
He had been preparing to use the house too.